Money management is far from universal; cultures worldwide have developed distinctive techniques for budgeting driven by local traditions, economic realities, and social values. From Japan’s detailed Kakeibo journaling to Kenya’s communal savings groups, these creative strategies blend practicality with cultural identity. Exploring such diverse approaches not only reveals surprising habits but also offers inspiration for anyone seeking fresh ideas for handling finances.

Julie Ann
· 4 min read
1. The Envelope System in Japan

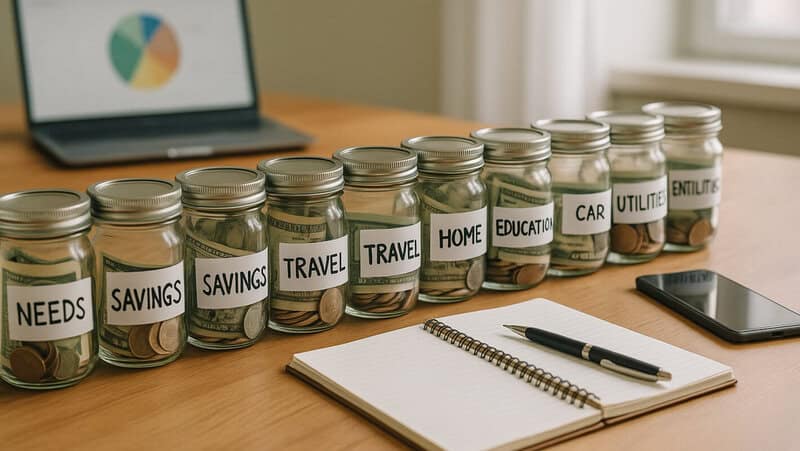
In Japan, the Kakeibo method helps individuals manage money by allocating cash into separate envelopes for categories like food, entertainment, and savings. This hands-on system encourages people to track spending closely, fostering greater awareness and discipline. Its straightforward, physical process has made Kakeibo popular beyond Japan, appealing to those seeking a practical way to control their finances. The method’s effectiveness and cultural roots have drawn global interest.
2. Rotating Savings Clubs in West Africa

In West Africa, tontines are popular savings clubs where members contribute a fixed sum on a regular basis. Each cycle, the collective pot is handed to a different participant, providing lump-sum access to funds. This system not only builds financial discipline but also strengthens community trust and mutual support. Similar group savings traditions, like susus in the Caribbean, highlight the global appeal of communal financial management.
3. Zero-Based Budgeting in the United States

Zero-based budgeting is a strategy where every dollar of income is assigned a specific purpose, ensuring that total income minus expenses equals zero. Popularized in the United States by finance gurus like Dave Ramsey, this method encourages disciplined spending and focused saving. Both households and businesses utilize this approach to eliminate waste and maximize financial efficiency.
4. 50/30/20 Rule in Australia

In Australia, many people adopt the 50/30/20 rule to manage their finances efficiently. This method allocates 50% of income to essential needs, 30% to personal wants, and 20% to savings or debt repayment. Originally popularized in the United States, the formula is widely recommended by Australian financial advisors for its simplicity and effectiveness. It offers a clear, balanced approach to spending and saving, making budgeting more accessible for individuals and families.
5. Collective Family Budgeting in India

In India, many families practice collective budgeting by pooling household incomes and making joint decisions about expenditures. This system, rooted in strong familial bonds, ensures that elders and dependents are financially supported and resources are optimized. Joint family budgeting is particularly prevalent in rural areas, where traditional values and shared responsibilities shape daily life. The approach highlights the importance of community and cooperation in personal finance.
6. Mobile Money Budgeting in Kenya

In Kenya, mobile money services like M-Pesa have transformed the way people budget and manage their finances. Users can send, receive, and save money directly through their mobile phones, making it easy to monitor spending and stick to budgets. This accessible technology has significantly boosted financial inclusion and budgeting discipline, particularly in rural and underserved areas. Kenya’s approach exemplifies how digital innovation can drive smarter money management.
7. Sixty-Day Budgeting in Germany

In Germany, many people prefer sixty-day budgeting, planning their finances over two months to better match salary cycles and anticipate large, irregular expenses such as insurance or holidays. This method encourages careful, advance planning and helps avoid financial surprises. Germans often use detailed spreadsheet templates to track their budgets, reflecting the country’s reputation for organization and precision.
8. Cash-Only Living in Argentina

Facing persistent economic instability and high inflation, many Argentinians rely on a cash-only approach for daily budgeting. By using physical currency, people can better track their spending, avoid costly bank fees, and reduce exposure to currency devaluation. This method encourages a heightened awareness of expenses and strict adherence to budgets. In contrast, digital payments remain less widespread compared to other countries.
9. The ‘Jars’ Method in the UK

In the UK, many households embrace the ‘jars’ method, distributing cash or digital funds into clearly labeled containers—either physical jars or digital “pots”—for specific expenses like groceries, utilities, or entertainment. This visual approach makes it easier to monitor spending and maintain control over different budget areas. Modern banks such as Monzo have popularized digital versions, helping users organize finances efficiently.
10. Social Saving Groups in the Philippines

In the Philippines, the ‘paluwagan’ system is a popular way for communities to save money together. Members contribute a set amount at regular intervals, with the pooled fund distributed to each participant in turn. This trusted, communal practice helps individuals achieve financial goals, handle emergencies, and foster mutual support—sharing similarities with rotating savings and credit associations (ROSCAs) found globally.
11. High-Tech Budgeting in Sweden

Sweden stands out for its embrace of cashless transactions and digital budgeting tools. Most Swedes rely on apps, digital wallets, and online banking platforms that offer automatic expense tracking, categorization, and real-time notifications. With banks integrating advanced budgeting features, managing money has become nearly effortless and highly transparent. This digital-first mindset has positioned Sweden as a global pioneer in modern personal finance.
Conclusion

The variety of budgeting methods found around the world reflects how financial habits are shaped by unique cultural and economic influences. From digital innovations to community-based traditions, these strategies reveal creative ways people manage money and support one another. Exploring global approaches can inspire us to rethink our own financial routines and adopt new practices. No matter the method, the universal importance of budgeting remains clear—it is essential for achieving stability, meeting goals, and building a healthy financial future.
Disclaimer

This article is for general informational purposes only and does not constitute financial advice. Please consult a qualified financial professional for advice tailored to your individual circumstances.


